An excursion into Markov chains - UNITEXT

Tell your friends about this item:
Ordered from remote warehouse
 Christmas presents can be returned until 31 January

Our customers say:
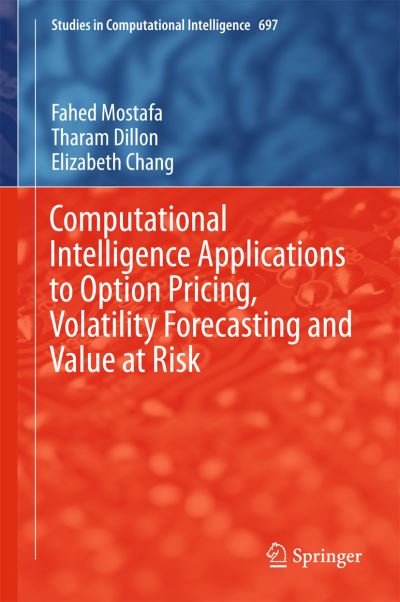
This book demonstrates the power of neural networks in learning complex behavior from the underlying financial time series data. The results presented also show how neural networks can successfully be applied to volatility modeling, option pricing, and value-at-risk modeling.
171 pages, 23 black & white illustrations, biography
| Media | Books Hardcover Book (Book with hard spine and cover) |
| Released | March 10, 2017 |
| ISBN13 | 9783319516660 |
| Publishers | Springer International Publishing AG |
| Pages | 171 |
| Dimensions | 155 × 235 × 13 mm · 435 g |
| Language | French |


